Showing posts with label car insurance. Show all posts

Wednesday, May 8, 2013

Who should YOU list on your automobile policy?

So, your sister is coming to visit you for a week or so and she may be driving your vehicle. You may wonder; "Should I call the insurance company to list my sister as a driver on my automobile policy?" 
For most insurance companies, the answer would be; No.

It is important to understand that you may not be required to list a driver on your automobile policy if you are lending your vehicle to a licensed friend or family member. Same reasoning applies to a short term visitor in your home who may loan the vehicle on one or two occasions during their visit. But remember, when you lend your vehicle.... you lend your insurance. If the driver has an accident while driving your car, the incident goes on YOUR insurance record.  

*Important*
"It is stated clearly in your automobile policy that as the policy holder, you have an obligation to advise your Insurance Broker of any driver(s) that have regular or frequent use of your vehicle."

If you do not disclose a driver either on the application or after your policy has been processed, it could mean major problems for you down the road when you may have to put in a claim. Your claim could either be denied or your policy could be cancelled all together.


Here are some examples that outline who should be listed as a driver on your automobile policy.

* Remember every insurance company may have different regulations so we strongly recommend that you speak with your automobile insurer* 

  1.  ANY licensed drivers living in your household
  2. The registered owner of the vehicle
  3. ANY licensed driver who has frequent or regular use of the vehicle. For example, driving the vehicle to school or to work several times a week
  4. ANY person using your car as a part of a car pooling arrangement 
  5. A car that is insured on your policy, but is garaged elsewhere with another driver; this driver must also be named on your policy. For example, your child who is away at school and using your vehicle while he/she is studying. 
Please contact your local broker for any questions you may have concerning who you should list on your automobile policy.


Monday, February 18, 2013

Recent regulations prohibit Canadians from driving in Florida - Insurance Implications??


Thursday morning February 14th, news hit that Canadians were technically no longer able to operate a motor vehicle in the sunshine state of Florida. Legislators passed a law that would require non-U.S motorists to have an international driver’s permit in addition to their regular driver’s license.  

Immediate action was taken by the federal government in order to ensure Canadians driving in Florida were protected. A decision has been made to suspend the law for all Canadian drivers. However, in March, the Florida Legislature will reconvene to view the legislation.

The Florida Department of Highway Safety and Motor Vehicles are proposing that Canadians should be given an official exemption from the law, which was originally put in place to help law enforcement interpret foreign licenses in other languages.

Following the announcement of the suspension, the Insurance Brokers Association of Ontario confirmed with the majority of insurance companies that they will not deny coverage.  Please contact your local insurance broker to specifically understand how your insurer will handle this situation.


Wednesday, October 31, 2012

Oh Sandy, Baby!

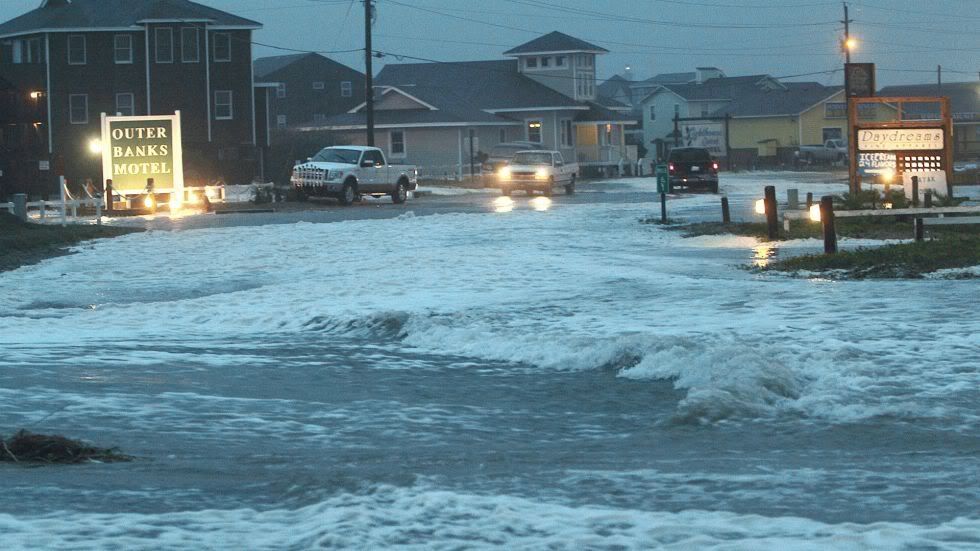
Tuesday afternoon, a post-tropical storm hit the northeastern United-States. Meteorologists are calling this one “Sandy”. So far, she’s been responsible for major flooding, power outages and at least 16 deaths. New York City has taken her wrath the hardest. Lower Manhattan is completely shut down; the subway systems are at a standstill and people are stuck inside their apartments waiting for the streets to clear. Vehicles that were once parked on the bustling streets of New York are now covered in seawater. 

This is an example of some of the flooding that resulted from Sandy.

The disastrous effects of the storm are now hitting close to home. Southern Ontario has experienced powerful wind gusts close to 80 kilometers per hour and between 20 to 40 millimeters of heavy rain fall.

Reports of vicious winds uprooting trees and destroying homes indicates, now more than ever, that Canada is susceptible to extreme weather conditions that can affect your livelihood, your safety and your home.

Being properly prepared with emergency and first aid kits is crucial when expecting these types of storms. Having enough water, food, extra blankets and clothing on hand will ensure proper safety for you and your family.   

After the storm has passed, it is of utmost importance that you inspect your property for any damages caused by the storm. You should be looking for such things as damage to your windows, doors and roof.

Contact your broker immediately for any questions concerning the effects of the storm and how to begin the claims process. 

* Keep in mind that damage caused by extreme winds are covered under a comprehensive property policy, however, only certain types of water damage are covered depending on the cause. As an example, if you have sewer backup coverage on your policy and the flooding causes the sewers to backup in to your basement, this type of water damage would be covered up to a certain limit. For more information on water losses click on this link.

Written by Genevieve St-Denis, Account Executive,
Rhodes & Williams Limited

Friday, March 30, 2012

Digging for Holes

It might sound a little funny if you were to tell someone that you are busy “digging for holes” but that’s a skill you practice everyday if you own a business. Part of the boss’s job is to snoop around and identify any holes in your operation; issues which could seriously harm your company.... Read the rest of Lorne's article at http://www.ourhomtetown.ca/ .

Wednesday, February 29, 2012

If I get pulled over in mum’s car (she has insurance, I’m not on it) do I get in trouble? Will rarely drive car."

I was recently asked a question on Twitter:

"Twittersphere: insurance?. If I get pulled over in mum’s car (she has insurance, I’m not on it) do I get in trouble? Will rarely drive car."

The direct answer to this question is that you do not need to be listed on a car insurance policy to be able to drive that car. You may borrow a friend’s car, family member’s car, etc. and it is not a requirement that you be listed on that policy. If a police officer pulls you over, what they are going to want to know is that there is insurance on the car. If proof of insurance (the "pink slip") is in the car, the police shouldn’t care if you are listed on the policy or not. There are always exceptions and qualifications to this statement. Obviously, you need to have been given permission to be using the car, and you need to be licensed to drive. Also, there is sometimes an exclusion put on a policy (called an OPCF 28a) to exclude specific drivers (which means if someone is excluded under a 28a, they would not have coverage should something happen to them or the car while driving it). Always discuss your specific situation with your Insurance Broker to make sure. This answer is general in nature and to make sure you are protected (and won’t get in trouble) in your specific situation, always talk to your Insurance provider (or your Mum’s in this case).

That all being said, it is important to ensure full disclosure by the person who does take out the insurance policy. One of the questions on an automobile application for insurance is, "Are there other’s in the household licensed to drive?" Most Insurance companies will want all drivers in the household listed on the policy, regardless of the frequency of use of the car. Make sure you answer all questions truthfully, and give full details so your insurance broker can help you find the best options specific to your situation.

One last point – there are circumstances where it would make sense to be listed on a family member’s insurance policy. It creates an insurance history and can help keep your premium’s down when you do get a car. Talk to an insurance broker and let them determine the best plan for you!

Friday, January 6, 2012

Insurance Fraud ... Be very AFra"u"d

There has been a lot in the news recently about the cost of insurance in Ontario.  Immediately I started seeing articles with many truth's peppered throughout the article filled with media hype and finger pointing.  One thing that is true is that insurance fraud is costing all Ontario insurance customers a lot of money.  Insurance Brokers have been talking about this for a long time and working on solutions.  Hopefully the most recent press will help draw attention to... and solution for the insurance fraud problem.

Below is a recent article by Deputy Senior Vice President of Claims for Intact Insurance, Sharon Bridge, regarding insurance fraud.  Intact is one of the many insurance companies with whom Rhodes & Williams Insurance Brokers can place insurance, if it is the best choice for our clients.

Detecting Insurance Fraud Controls Claims Costs

--------------------------------------------------------------------------------
Deputy Senior Vice President, Claims Sharon Bridge explains why and how Intact Insurance, the industry and the Ontario government are working together to reduce abuse of the claims system.

With catastrophic weather events on the rise – like April’s severe hailstorms in Thunder Bay and Stratford, wild windstorms in the Ottawa and Niagara regions and Goderich Tornado – the last thing consumers need is added costs due to increased auto insurance fraud. But that’s exactly what’s happening in Ontario.

“Auto insurance fraud has been on the rise, particularly in the GTA,” says Sharon Bridge, who’s been leading Intact’s claims transformation in Ontario over the years. “The previous accident benefits system led to the prevalence of increased abuse committed by various parties involved in the claims process and increased the cost of injury claims costs. These trends adversely affected consumers as premiums rose.

”Abuse and fraud is an issue that affects the cost of protecting people, so we’re tackling it head on. Our proactive approach to fraud management involves investing in people, technology and infrastructure to help manage, detect and prevent fraudulent or improper activities. It’s an approach that we developed with the customer in mind. Putting the customer at the centre of everything we do is what the Intact Insurance brand is all about and these actions help us get customers back on track as quickly as possible by ensuring that they get the right kind of treatment by the right practitioners for full and fast recovery.”

“Tackling fraud is a complex, long¬-term fight, but with the government willingness to take action, it’s one we intend to win. The Ontario Auto Reform, adopted last year, gives us more time to respond to treatment plans and identify inappropriate and abusive requests. What we need in the longer term are greater consequences for the perpetrators of fraud and abuse.”

The industry is working together to fight the problem of fraud and limit the impact it has on premiums.

Intact welcomes the establishment of the Ontario government’s Anti-Fraud Task Force that has made recommendations about detection, investigation and enforcement. “The task force is a step in the right direction given that fraud is omnipresent, puts innocent people at risk and increases insurance premiums,” Bridge continued.

Wednesday, April 8, 2009

Rental Car Insurance Coverage - Are you Covered

If you have rental car coverage on your automobile insurance policy, and you go and rent a uhaul cargo van or pick-up truck - are you covered? What do you think?

This is not an easy question and is misunderstood by most. The safest route is to talk to your insurance broker before assuming anything is covered ... that is what we are here for. That being said, here is the basic answer:

The rental car coverage on your auto policy is designed for when you rent a personal vehicle, and not for most trucks and vans that you might hire for a move. As a result, there are some exclusions that would apply. Here are the main ones that would apply:

  1. The coverage would not apply to any vehicle with a gross vehicle weight rating over 4500kg (that would exclude most moving trucks and large vans) (check your specific policy wordings to confirm exclusions)
  2. The coverage would not extend to carrying passengers or commercial use of the rented vehicle, in case you were running errands for your business.
  3. The coverage is restricted to only those people named on the underlying policy.
  4. Note that there is also a dollar limit to the coverage that might be an issue.

So as mentioned, every situation is unique, so give us a call to make sure.

Of note, one of the recommendations put forth in the Report on the Five Year Review of Automobile Insurance, presented to the Financial Services Commission of Ontario is as follows:

"The superintendent intends to amend the OAP 1 to provide a limited amount of coverage for vehicles with a GVWR over 4,500 kg's."

This is just a recommendation and has not been adopted, so ensure you are properly covered.