Showing posts with label liability. Show all posts

Thursday, June 13, 2013

Our blog has moved!

moved,moving,moving truck,moving trucks,moving van,moving vans,phrases,signs,text,transportation,trucks,vans,vehicles,we have moved,we've moved

We will now be blogging from the Rhodes & Williams learning center!

Come check out our completely revamped website and Learning Center for the most up-to-date tips and information surrounding the insurance industry.

We hope our Learning Center will help ensure you are informed and protected.

Visit our new blog spot

Visit our Learning Center 

Friday, November 23, 2012

LISTEN UP! All current and future condo owners!!

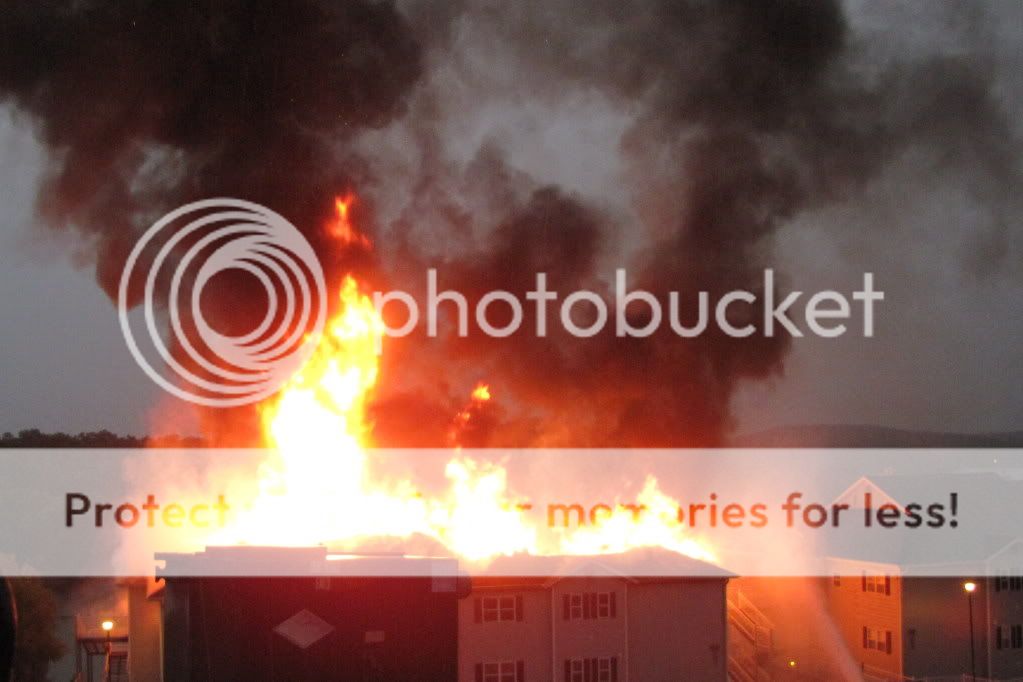
Have you ever wondered what would happen if the unit next to you went up in flames or had a pipe that burst, severely damaging other units in your complex? It may not seem like something that could happen to you, but I’m here to tell you it can!

Imagine one day; the unthinkable happens. The woman next door was in such a hurry trying to get to work in the morning she left her stove on HIGH!! Her unit goes up in flames and all the units next to her are burnt to the ground. Including yours! You get home from work only to find your beautiful home in utter disarray. The final flames are being put out by the fire fighters.  All your belongings… gone. You lost everything. Clothes, furniture, appliances, family photos…AND you just put in those new hardwood floors!


Not to worry, you purchased a comprehensive condo policy. Your insurance company will pick up the bill, but you might wonder, who’s going to pay to replace the building itself?

The condo corporation of course! Think again… they do have a policy set in place to cover the cost of rebuilding but who’s on the hook to pay the deductible to the condo corporation’s policy? Surprise! YOU ARE! And it’s not a small amount.

The condo corporation can ask every condo owner to cover the cost of their deductible. Sometimes you’re looking at anywhere between $5,000- $20,000 per condo owner. I don’t know about you, but I sure don’t have $20,000 sitting in the bank waiting to pay a deductible for fire I didn’t even cause! 

So where do you go from here? Well there’s actually an easy fix! Some insurance companies will cover the cost of the condo corporation’s deductible under your own policy up to a certain limit. 

Contact your local broker to discuss the coverage’s under your condominium policy.


Written by Genevieve St-Denis, Account Executive,
Rhodes & Williams Limited

Thursday, November 8, 2012

Is your pet insured on your homeowner’s policy?

Some of you may remember the story of the sales associate at Home Depot who was bit by a customer’s Shih Tzu last summer.  She was bending down to pet the dog when it leaped out and bit her right in the face! The woman sustained severe injuries from the little pup and required plastic surgery in order to fix her torn off nose. 

 
The photo above is a Shih-Tzu; the same breed that is
responsible for the attack of the Home Depot Associate.

Regardless of the size, any dog can be dangerous.
 The 66-year-old customer was fined $610 by a bylaw officer and ordered to keep her 12-year-old Shih Tzu muzzled at all times in public.    

Even though the customer was reprimanded for her dog’s actions, the Home Depot employee still decided to take legal action against the dog’s owner. 

In this case, the employee would have sued against the Personal Liability portion of thecustomer’s property policy for the actions of the dog. Keep in mind that every claim is investigated on a case by case basis and that all insurance companies have different exclusions.In this situation, the insuring company did pay out the claim, however the amount was undisclosed. 

It’s important to know that a situation resulting in a liability claim can happen anywhere at anytime. Therefore, it’s important to have sufficient liability coverage on your tenants, condo or homeowners policy. In this case, it benefited the customer greatly as she did not have to bear the cost of the settlement.  

Contact your local broker for more information on liability coverage. 

*Please note that your pet is not insured on your policy as property. Meaning you would have no coverage for health benefits for your animal or coverage if they were to be stolen. 

Written by Genevieve St-Denis, Account Executive,
Rhodes & Williams Limited

Thursday, October 18, 2012

Employment Practices Insurance

Lorne Wiebe has written another article about issues important to business owners, for the local online hub serving Cornwall, Stormont, Dundas & Glengarry - http://www.ourhometown.ca . What follows is an introduction to that article. The full article can be read in his column, "Risky Business"

Employment Practices Insurance

Twenty years ago, business owners wouldn’t have given it a second thought but in today’s world where we’ve been taught to stand up for our “rights” it’s a whole new world and that has lead to a relatively new type of business risk. If you run a company which employs any number of people - from 1 to 10,000 - you need to know the ins-and-outs of today’s employment practices; everything from hiring to firing and conduct in the workplace. Whether you are bringing in someone new or exiting a current employee, there are certain rules in place (mandated by law) to make sure that everything is fair and on the up-and-up. And these rules don’t apply only to management; even if one of your employees steps out-of-bounds, you could be held accountable and your business could at risk.......

Continue Reading

Friday, June 8, 2012

Free, Public Wi-Fi Can be Dangerous to Your Health

This guest blog comes from Steve Anderson. Steve provides useful tips and information that can help generate revenues and prevent loss.

A few days ago I was sitting at a local coffee shop and watched a young lady come in with her laptop. She sat down at the table, connected her laptop to the free wireless network, and proceeded to log into her online bank account. I remember thinking at the time, "That is a dangerous practice."

I then received an email from Steve Aronson, an agent in Massachusetts, highlighting the same issue. He suggested I write about how to protect your information when using free public Wi-Fi.

Wireless access to the Internet has become a necessity for many people so they can stay connected. Whether you're on vacation at a resort, waiting in an airport or sitting in a coffee shop, it's likely you will be able to connect to the Internet through a wireless network provided by the property owner. Sometimes these will be offered for a small fee and sometimes they will be free.

But be careful: sometimes free Wi-Fi can be a scam perpetrated by criminals hoping to steal your personal information. You could end up being the target of a "man in the middle" attack, in which a hacker is able to steal the information you send over the Internet, including usernames and passwords. And you could also have your files and identity stolen and end up with a spyware-infested computer. The attack could even leave your laptop open to hackers every time you turn it on, by allowing anyone to connect to it without your knowledge.


How the attack works

You go to an airport or other hot spot and fire up your PC, hoping to find a free hot spot. You see one that calls itself "Free Wi-Fi" or a similar name. You connect. Bingo -- you've been had!

The problem is that it's not really a hot spot. Instead, it's an ad hoc, peer-to-peer network, possibly set up as a trap by someone with a laptop nearby. You can use the Internet, because the attacker has set up his PC to let you browse the Internet via his connection. But because you're using his connection, all your traffic goes through his PC, so he can see everything you do online, including all the usernames and passwords you enter for financial and other websites.

In addition, because you've directly connected to the attack PC on a peer-to-peer basis, if you've set up your PC to allow file sharing, the attacker can have complete run of your PC, stealing files and data and planting malware on it.

You can't actually see any of this happening, so you'd be none the wiser. The hacker steals what he wants to or plants malware, such as zombie software, then leaves, and you have no way of tracking him down.

All that is bad enough, but it might not be the end of the attack. Depending on how you've connected to that ad hoc network, the next time you turn on your PC, it may automatically broadcast the new "Free Wi-Fi" network ID to the world, and anyone nearby can connect to it in ad hoc peer-to-peer mode without your knowledge -- and can do damage if you've allowed file sharing.

Security company Commtouch (previously Authentium Inc.) has found dozens of ad hoc networks in Atlanta's airport, New York's LaGuardia, the West Palm Beach, Fla., airport and Chicago's O'Hare. Internet users have reported finding them at LAX airport in Los Angeles.

Commtouch did an in-depth survey of the ad hoc networks found at O'Hare, visiting on three different occasions. It found more than 20 ad hoc networks each time, with 80% of them advertising free Wi-Fi access. The company also found that many of the networks were displaying fake or misleading MAC addresses, a clear sign that they were bent on mischief.


How to protect yourself

The easiest way to protect yourself from Wi-Fi fraud is to not connect to any free wireless networks. If you're in a coffee shop, airport or hotel that has a legitimate Wi-Fi connection for a small fee, it's worth the price for peace of mind. Ask the business' staff if there is a hot spot available and get the name from them.

Mobile device users should make sure they have downloaded all the security updates for their operating systems.

If you function in a wireless environment on a regular basis, you are better off spending the money on a wireless card that you get through AT&T, Verizon or Sprint. This way, you have your own relatively secured wireless connection. This is what I do for access.

If you choose to take advantage of free Wi-Fi availability, here are some things to keep in mind.
  • Never connect to a "computer-to-computer" network. When choosing a wireless network, check out the description of each one. A normal wireless network is simply called "wireless network" not a "computer-to-computer" network.
  • Use HTTPS to access webmail and avoid protocols that don't include encryption.
  • Turn off your computer's file sharing capabilities. The instructions will vary slightly depending on what computer system you're using (Windows XP, Vista, Windows 7, etc.).
  • Use a software firewall to further control who can connect to your computer and how.
  • Avoid conducting financial transactions or accessing any sensitive websites if you aren't using an Internet connection that you know and trust.
It pays to be vigilant whenever you are connecting to a wireless network. If you have any doubt about the Wi-Fi connections, then don't connect. It's just not worth the potential problems.