Thursday, June 13, 2013

Our blog has moved!

moved,moving,moving truck,moving trucks,moving van,moving vans,phrases,signs,text,transportation,trucks,vans,vehicles,we have moved,we've moved

We will now be blogging from the Rhodes & Williams learning center!

Come check out our completely revamped website and Learning Center for the most up-to-date tips and information surrounding the insurance industry.

We hope our Learning Center will help ensure you are informed and protected.

Visit our new blog spot

Visit our Learning Center 

Tuesday, May 14, 2013

What you need to know this SPRING!

With the warm weather finally making an appearance, it’s time to start thinking about spring maintenance of your home.

It is important to ensure proper maintenance practices and inspect your home on a regular basis in order to avoid future claims and problems.

Here are a couple quick tips to keep your home in working condition;


1.       Check and clean your furnace air filters 
2.       Clean or replace your air-conditioning filter
3.       Check your smoke, carbon monoxide and security alarms and replace the batteries
4.       Clean your windows, screens and hardware. 
5.       Examine your foundation walls for cracks, leaks or signs of moisture. 
6.       Clear all drainage ditches and eaves troughs of debris   
7.       Ensure that your downspouts are directed away from your foundation

Stayed tuned for more great tips on summer maintenance!!!


Written by Geneviève St-Denis,
Rhodes & Williams Insurance

Wednesday, May 8, 2013

Who should YOU list on your automobile policy?

So, your sister is coming to visit you for a week or so and she may be driving your vehicle. You may wonder; "Should I call the insurance company to list my sister as a driver on my automobile policy?" 
For most insurance companies, the answer would be; No.

It is important to understand that you may not be required to list a driver on your automobile policy if you are lending your vehicle to a licensed friend or family member. Same reasoning applies to a short term visitor in your home who may loan the vehicle on one or two occasions during their visit. But remember, when you lend your vehicle.... you lend your insurance. If the driver has an accident while driving your car, the incident goes on YOUR insurance record.  

*Important*
"It is stated clearly in your automobile policy that as the policy holder, you have an obligation to advise your Insurance Broker of any driver(s) that have regular or frequent use of your vehicle."

If you do not disclose a driver either on the application or after your policy has been processed, it could mean major problems for you down the road when you may have to put in a claim. Your claim could either be denied or your policy could be cancelled all together.


Here are some examples that outline who should be listed as a driver on your automobile policy.

* Remember every insurance company may have different regulations so we strongly recommend that you speak with your automobile insurer* 

  1.  ANY licensed drivers living in your household
  2. The registered owner of the vehicle
  3. ANY licensed driver who has frequent or regular use of the vehicle. For example, driving the vehicle to school or to work several times a week
  4. ANY person using your car as a part of a car pooling arrangement 
  5. A car that is insured on your policy, but is garaged elsewhere with another driver; this driver must also be named on your policy. For example, your child who is away at school and using your vehicle while he/she is studying. 
Please contact your local broker for any questions you may have concerning who you should list on your automobile policy.


Tuesday, April 9, 2013

One Size Doesn’t Fit All

If you run your own business, you know that it’s unique. Not all restaurants, for example, serve the same food to the same people during the same hours in the same neighborhood  Some offer take out while others don’t. Some only serve breakfast and lunch while others only serve dinner. And so it goes with whatever type of business you operate and that’s why it’s critically important that your insurance broker fully understands the full scope of your operation. If they don’t, they won’t be able to ensure that your business exposures are properly covered. If your broker doesn't know your business, the consequences can be serious. 
Written By Lorne Wiebe,
Rhodes & Williams Account Executive.

Photo credit: ourhometown.ca

For example, it’s possible that a food manufacturer doesn't have insurance to cover the cost of having to recall a defective product that it has shipped to market. It’s possible that a contractor which operates at an airport doesn't have coverage for any business it conducts at the airport. And it is also possible that a wholesaler which exports a good chunk of its products to the U-S doesn't have any insurance coverage for that arm of its business. How do I know that these scenarios are all possible? Because these are just a few of the real-life situations I've discovered as I've been reviewing the existing insurance policies of potential customers.

Unfortunately, the business owners in all of these cases had no idea that there were gaping holes in their policies. When I asked them if their insurance broker fully understood their business operation, each of them admitted that they probably didn't.

The blame here lies mostly at the feet of the brokers who do not dig deep enough when they meet with their clients. Does your broker know your business?
Every time you meet with your broker (and it should be at least a couple of times a year) he or she should be asking you a lot of questions. Are your business revenue projections still on track? Have you been hiring or reducing your workforce? Is your business providing any new services or products and conversely, has it withdrawn any from the marketplace? What are your future plans? Has your business’s online activity changed? All of these questions and about a dozen more should be a part of your typical broker conversation.

In the cases above, if the broker knew that the contractor had taken on work at an airport and that the wholesaler had begun exporting products to the U-S, they could have easily found coverage, however either the broker didn’t ask or their client didn’t think it was important for them to know. It really all comes down to the relationship that you have with your broker. That’s one of the reasons why Rhodes & Williams Ltd has a formal “Client Service Plan” which includes a mid-year client review. The free flow of information and advice throughout the year is a pretty good litmus test on how your broker relationship is going. If you don’t hear from your broker except when they want money at renewal, it’s time to find someone else. 

Wednesday, March 6, 2013

Planning a trip this March break?


With your vacation right around the corner, you are busy preparing everything that goes along with taking off to a sunny destination; getting the whole family packed, running around to pick up the last couple items needed and confirming your reservations with the airlines/hotels are only but a couple things that you have to do before jetting away.

But before you jump on that plane, have you thought about travel and health insurance?  

Although our provincial health plan may cover certain unforeseen costs that may be incurred while travelling it doesn’t always cover out-of-country travel.  

As an example, you and your family are travelling to a sunny destination such as Mexico and someone in your party severely injures themselves while out on an excursion. They would require immediate medical evacuation which can run upwards of $50,000. In this case, the provincial health plan will only cover part of the bill and will not pay for the expense up front.  Therefore, it is extremely important to purchase private travel health insurance and to verify the conditions, limitations and requirements of your plan before your departure.

Here are a couple things to look out for when purchasing a travel health insurance plan; 

1. The plan has 24/7 emergency contact numbers in English or French or translation services for health care providers in your destination country
2. Pays for foreign hospitalization for illness or injury and related medical costs
3. Provides coverage for health care provider’s visit and prescription medicines
4. Provides direct payment of bill and cash advances abroad so you don’t incur the expense
5. Clearly outlines deductible costs
6. Covers emergency transportation, such as ambulance services
7. Provides for medical evacuation to Canada
Be sure to carry proof of your private travel health insurance and the emergency contact numbers at all times during your vacation.

Safe travels! 


Written by Geneviève St-Denis, Account Executive, Rhodes & Williams


Monday, February 18, 2013

Recent regulations prohibit Canadians from driving in Florida - Insurance Implications??


Thursday morning February 14th, news hit that Canadians were technically no longer able to operate a motor vehicle in the sunshine state of Florida. Legislators passed a law that would require non-U.S motorists to have an international driver’s permit in addition to their regular driver’s license.  

Immediate action was taken by the federal government in order to ensure Canadians driving in Florida were protected. A decision has been made to suspend the law for all Canadian drivers. However, in March, the Florida Legislature will reconvene to view the legislation.

The Florida Department of Highway Safety and Motor Vehicles are proposing that Canadians should be given an official exemption from the law, which was originally put in place to help law enforcement interpret foreign licenses in other languages.

Following the announcement of the suspension, the Insurance Brokers Association of Ontario confirmed with the majority of insurance companies that they will not deny coverage.  Please contact your local insurance broker to specifically understand how your insurer will handle this situation.


Thursday, February 14, 2013

What YOU need to know about your Valentine’s Day purchases!


With Valentines Day right around the corner, you may be planning a trip to the jewelry store.  Getting your special someone a sparkling gem is very exciting!!  So…in light of the up coming festivities, I will be pointing out some great tips on ensuring your jewelry is adequately covered just in time for the 14th of February!!

Although basic tenants, condo or homeowners insurance might include a limited amount of coverage for jewelry, the coverage is best purchased as an extension, or floater, to your property policy.  A current appraisal is often a requirement however this is something that is commonly provided by the jeweler at the time of purchase.  

Now read very closely. THE BIGGGEST reason why you want to schedule an item is simply because, if a diamond or stone goes missing, it gets replaced and covered for the FULL appraised value.  An added bonus is that the deductible does not apply to this type of claim.

It’s important to keep in mind that jewelry should be appraised periodically to accommodate fluctuation in value and to protect your investment.

Remember, it is of utmost importance to call your Insurance Broker should the value of your item increase.

Happy Valentine’s Day to all you lovers out there!!


Written by Geneviève St-Denis, Account Executive, Rhodes & Williams


Thursday, January 24, 2013

The Dangers Of Driving

"..driving alert is driving safe"


A recent tragedy has hit close to home. A tour bus crashed killing seven Canadians on a trip from British Columbia to Las Vegas. The bus, carrying 47 passengers, crashed near a cliff after veering off icy roads.
Image by "Salvatore Vuono" from www.freedigitalphotos.net
The Vancouver travel company is now being sued by two survivors of the accident.  They claim the bus driver violated American federal laws by working 90 to 100 hours during the first eight days of their trip.  They indicate in the lawsuit that the tour company’s driver seemed extremely fatigued and ignored evident dangerous road conditions.

After the driver lost control, the bus spun and crashed through the guard rail. There were 9 fatalities and 38 others were hurt.  Although this is an extreme case of getting behind the wheel of a vehicle without acknowledging ones mental and physical capabilities to drive, this is a subject that relates to all Canadian drivers. 

All drivers should be aware of their mental and physical state before operating a vehicle. Being overly tired and drowsy is a “silent killer”.  Drivers’ nodding off while at the wheel leads to fatal accidents. Some of the signs you should look out for besides the obvious ones of yawning and heavy eyelids, are daydreaming, missing road signs or exits and feeling irritable and restless. If you experience any of the mental or physical signs of exhaustion, pull over to the side of the road immediately and phone a relative or a friend to come help. In the event that you are out of town, you can call a tow truck to come help you in this type of situation.

And remember, driving alert is driving safe.


Wednesday, January 16, 2013

Buidling a Brighter Future, The Final Day

Rachel McCullys' trip to Nicaragua has concluded. She has arrived back to her home in Ottawa and also back to the Rhodes & Williams Office.  Below is a blog that Rachel has written about her final day of helping to build a School for the community of El Sasle.
Nicarag

We knew the day would be good when breakfast was served: pancakes and watermelon salad.  After breakfast, Gregorio the engineer took us back to the job site on the scenic route (otherwise known as mud alley). Along the way we saw royal lemons the size of a grapefruit, a variety of cacti and a plant that shrinks to the touch.  Kelly McKinney also led us through a surprise session of "Kelly-thetics", otherwise known as a massage circle to get our shoulders ready for the day.

Then Gregorio numbered us off and we were put into 3 teams: Team 1 Rebar, Team 2 Leveling the classroom floor and surprise, surprise, Team 3 Cement!

Team 1 Rebar, powered through creating the forms for the back slope and finished in record time!  Despite finishing their assigned task early, they were soon asked to move 1,200 clay tiles. When moving one stack, a scorpion emerged. Before we could get a clear photo, our local hero swooped in and eliminated the threat.

Team 2 Levelers, MacGyver'd some much needed tools to help level and stamp the sticky red clay used to form the floor in the classroom.  Here's something funny about that clay.  Most of you will recall that expression "Ants in your pants," well Christine understood the literal meaning of that expression when she sat in the pile of clay on the return trip from the quarry. Upon this discovery, Chico advised the best remedy was to stand under running water. Christine sprinted to the shower only to find there was no running water.

Team 3 Cement,  mixed 8 pans and finished the back slope all while incorporating cement mixing competitions and humorous exchanges all day long. By the end of the day, all teams were working together on the cement.

Rachel 2012We finished the work day a little early and had time to visit with a local family. Rachel McCully, Rhodes & Williams, was impressed with the tight knit family values.  "It was interesting to hear from the 75 year old patriarch who fathered 15 children, each of whom worked together to ensure family priorities were met. Two of the sons were Contra soldiers in the war, while their home was located in the Sandanista territory, placing the family in a dangerous position. The father's response was to this unfortunate arrangement was "war is not delicious" which left us all in tears.".....

                                                         Continue Reading This Blog


Friday, January 11, 2013

Building a Brighter Future Part 2

Last month we posted an article on our website about one of our team memebers upcoming journey to Nicaragua. If you havent had a chance to read it you can do so here.
Rachel McCully has arrived in Nicaragua where she will be helping to build a school for the community. A blog has been posted each day since the team arrived to Nicaragua, they can be read below.

Day 4

We are very proud of Rachel. We are looking forward to seeing the progress of her and the other indivuals who are helping build this school. Please stay tuned for future updates.  


"...I am very excited to be part of this amazing project and know that this will be a life changing experience"

-Rachel McCully

Wednesday, January 9, 2013

Going out of town? Make sure your home is protected!

Imagine coming home from a nice relaxing vacation, to find a foot of water in your house! Not a pleasant welcome home!

What happened? A pipe has burst and the water has been running out of it ever since! A 1/8-inch crack in a pipe can spill 250 gallons of water a day. That’s a lot of water where you don’t want it to be!

Why would a pipe burst? If the pipe gets cold, the water in the pipe freezes, and water expands when it freezes. This causes the pipe to burst. It can happen to copper or plastic pipes, old or new.

How would a pipe get too cold? The answer is simple--there is not enough heat in the home. The cause of the loss of heat could be the oil or propane running out, a power outage, or just having the temperature set too low.

Is it covered?  Check with your insurance company on their requirements when you are away. Some insurers require that the home be checked, but you will need to confirm with them how often. If the home can’t be checked, some insurers will require that you turn off the water and drain the pipes. To drain the system, you need to shut off the water supply and turn on every tap until the water stops running. This way, there is no water in the pipes, so they can’t freeze.

It can be extremely costly to have to replace everything ruined by the water, not to mention a health risk due to mold. You don’t want to come home to that!


Written by Sandy Bafia, Account Manager Rhodes & Williams Limited


Monday, January 7, 2013

Insurance is Just a Part of it

Rhodes Williams

Lorne Wiebe has written another article about issues important to business owners, for the local online hub serving Cornwall, Stormont, Dundas & Glengarry - http://www.ourhometown.ca . What follows is an introduction to that article. The full article can be read in his column, "Risky Business"


A Sign of the Times
Photo Credit ourhometown.ca

"..if all you are hearing from your broker is that you “need more insurance” perhaps it’s time to find a different broker"


When it comes to protecting your business from the hundreds of risks it faces everyday, you might expect an insurance broker (guilty as charged) to offer a one-word solution…insurance. But that isn’t the case – or at least it shouldn’t be. Your insurance broker needs to point out a whole list of other options for you whenever the discussion revolves around protecting your company.

We use a handy little chart at Rhodes & Williams Ltd. which spells out all of your potential protection options, including risk avoidance, risk mitigation, risk transfer and even risk acceptance. I won’t dig deep into all of these risk management options because each of them is a discussion as long as your arm and not all of them apply to every business situation but knowing just a few of them might make you think about your operation a bit differently.....

Continue Reading

Friday, November 23, 2012

LISTEN UP! All current and future condo owners!!

Have you ever wondered what would happen if the unit next to you went up in flames or had a pipe that burst, severely damaging other units in your complex? It may not seem like something that could happen to you, but I’m here to tell you it can!

Imagine one day; the unthinkable happens. The woman next door was in such a hurry trying to get to work in the morning she left her stove on HIGH!! Her unit goes up in flames and all the units next to her are burnt to the ground. Including yours! You get home from work only to find your beautiful home in utter disarray. The final flames are being put out by the fire fighters.  All your belongings… gone. You lost everything. Clothes, furniture, appliances, family photos…AND you just put in those new hardwood floors!


Not to worry, you purchased a comprehensive condo policy. Your insurance company will pick up the bill, but you might wonder, who’s going to pay to replace the building itself?

The condo corporation of course! Think again… they do have a policy set in place to cover the cost of rebuilding but who’s on the hook to pay the deductible to the condo corporation’s policy? Surprise! YOU ARE! And it’s not a small amount.

The condo corporation can ask every condo owner to cover the cost of their deductible. Sometimes you’re looking at anywhere between $5,000- $20,000 per condo owner. I don’t know about you, but I sure don’t have $20,000 sitting in the bank waiting to pay a deductible for fire I didn’t even cause! 

So where do you go from here? Well there’s actually an easy fix! Some insurance companies will cover the cost of the condo corporation’s deductible under your own policy up to a certain limit. 

Contact your local broker to discuss the coverage’s under your condominium policy.


Written by Genevieve St-Denis, Account Executive,
Rhodes & Williams Limited

Thursday, November 8, 2012

Is your pet insured on your homeowner’s policy?

Some of you may remember the story of the sales associate at Home Depot who was bit by a customer’s Shih Tzu last summer.  She was bending down to pet the dog when it leaped out and bit her right in the face! The woman sustained severe injuries from the little pup and required plastic surgery in order to fix her torn off nose. 

 
The photo above is a Shih-Tzu; the same breed that is
responsible for the attack of the Home Depot Associate.

Regardless of the size, any dog can be dangerous.
 The 66-year-old customer was fined $610 by a bylaw officer and ordered to keep her 12-year-old Shih Tzu muzzled at all times in public.    

Even though the customer was reprimanded for her dog’s actions, the Home Depot employee still decided to take legal action against the dog’s owner. 

In this case, the employee would have sued against the Personal Liability portion of thecustomer’s property policy for the actions of the dog. Keep in mind that every claim is investigated on a case by case basis and that all insurance companies have different exclusions.In this situation, the insuring company did pay out the claim, however the amount was undisclosed. 

It’s important to know that a situation resulting in a liability claim can happen anywhere at anytime. Therefore, it’s important to have sufficient liability coverage on your tenants, condo or homeowners policy. In this case, it benefited the customer greatly as she did not have to bear the cost of the settlement.  

Contact your local broker for more information on liability coverage. 

*Please note that your pet is not insured on your policy as property. Meaning you would have no coverage for health benefits for your animal or coverage if they were to be stolen. 

Written by Genevieve St-Denis, Account Executive,
Rhodes & Williams Limited

Wednesday, October 31, 2012

Oh Sandy, Baby!

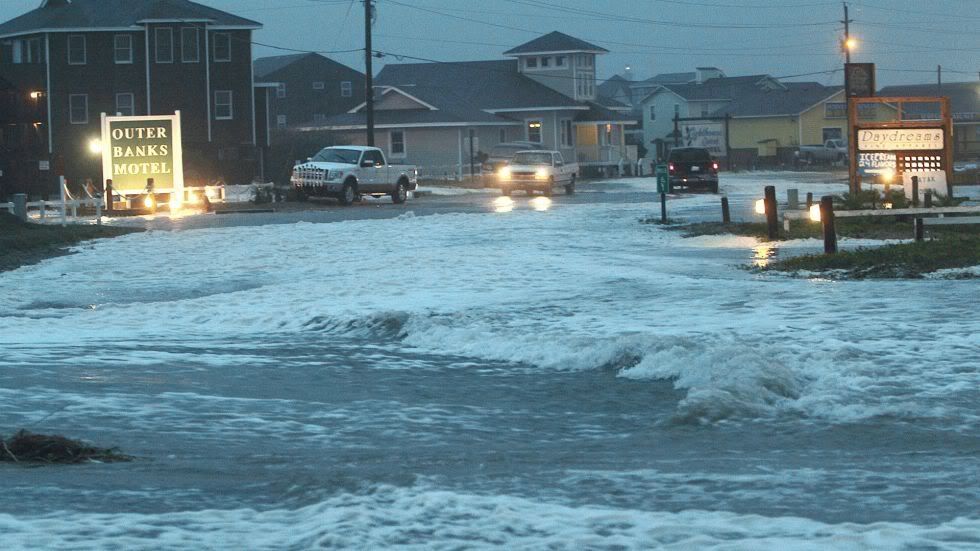
Tuesday afternoon, a post-tropical storm hit the northeastern United-States. Meteorologists are calling this one “Sandy”. So far, she’s been responsible for major flooding, power outages and at least 16 deaths. New York City has taken her wrath the hardest. Lower Manhattan is completely shut down; the subway systems are at a standstill and people are stuck inside their apartments waiting for the streets to clear. Vehicles that were once parked on the bustling streets of New York are now covered in seawater. 

This is an example of some of the flooding that resulted from Sandy.

The disastrous effects of the storm are now hitting close to home. Southern Ontario has experienced powerful wind gusts close to 80 kilometers per hour and between 20 to 40 millimeters of heavy rain fall.

Reports of vicious winds uprooting trees and destroying homes indicates, now more than ever, that Canada is susceptible to extreme weather conditions that can affect your livelihood, your safety and your home.

Being properly prepared with emergency and first aid kits is crucial when expecting these types of storms. Having enough water, food, extra blankets and clothing on hand will ensure proper safety for you and your family.   

After the storm has passed, it is of utmost importance that you inspect your property for any damages caused by the storm. You should be looking for such things as damage to your windows, doors and roof.

Contact your broker immediately for any questions concerning the effects of the storm and how to begin the claims process

* Keep in mind that damage caused by extreme winds are covered under a comprehensive property policy, however, only certain types of water damage are covered depending on the cause. As an example, if you have sewer backup coverage on your policy and the flooding causes the sewers to backup in to your basement, this type of water damage would be covered up to a certain limit. For more information on water losses click on this link.

Written by Genevieve St-Denis, Account Executive,
Rhodes & Williams Limited

Thursday, October 18, 2012

Employment Practices Insurance

Lorne Wiebe has written another article about issues important to business owners, for the local online hub serving Cornwall, Stormont, Dundas & Glengarry - http://www.ourhometown.ca . What follows is an introduction to that article. The full article can be read in his column, "Risky Business"

Employment Practices Insurance

Twenty years ago, business owners wouldn’t have given it a second thought but in today’s world where we’ve been taught to stand up for our “rights” it’s a whole new world and that has lead to a relatively new type of business risk. If you run a company which employs any number of people - from 1 to 10,000 - you need to know the ins-and-outs of today’s employment practices; everything from hiring to firing and conduct in the workplace. Whether you are bringing in someone new or exiting a current employee, there are certain rules in place (mandated by law) to make sure that everything is fair and on the up-and-up. And these rules don’t apply only to management; even if one of your employees steps out-of-bounds, you could be held accountable and your business could at risk.......

Continue Reading

Friday, October 12, 2012

Do you have signage on your vehicle? Here’s what YOU need to know!

Although signage on a vehicle may indicate that it is being used for business purposes, signage does not determine the classification of the vehicle.  The broker or insuring company would typically determine the correct use of the vehicle during the quoting process

Making sure your vehicle is being properly rated is very important regardless of signage. If you’re using your vehicle for business purposes but fail to disclose the correct use of the vehicle to your broker, this could result in a potential claim being denied.

Here’s an example to help illustrate this point; 

A stay-at-home mom has a small home-based business baking sugary sweets. She uses her vehicle to deliver her homemade treats to local businesses. Her vehicle is only being rated as personal use. If she were to be involved in an accident while commuting to a location to deliver her baked goods, the insurance company may deny her claim seeing the vehicle wasn’t properly rated. In this case, her vehicle should have been rated for occasional business use. The annual mileage used for business purposes will also determine the correct classification for business use of the vehicle.

Contact your local broker for any questions concerning personal or business use on your vehicle.

Thursday, September 13, 2012

We All Make Mistakes

Lorne Wiebe has written another article about issues important to business owners, for the local online hub serving Cornwall, Stormont, Dundas & Glengarry - http://www.ourhometown.ca . What follows is an introduction to that article. The full article can be read in his column, "Risky Business"

 
A Sign of the Times
Photo Credit - ourhometown.ca

Years ago I worked for a boss who used to say “It’s okay to make as many mistakes as you want…just don’t make the same mistake twice.” While the sentiment that you’re allowed to make mistakes and then learn from them is nice, when it comes to the services that your business provides for others, most clients won’t be that forgiving if your mistakes cost them money.

At some point, everyone and every company is going to make a mistake. Either we do something that we shouldn’t do or we don’t do something that we should have done. That’s life. We already are accustomed to the thinking that our mistakes could hurt some “body” (bodily injury) or some “thing” (property damage) and most businesses purchase a Commercial General Liability insurance policy which protects them in those instances. But how can you protect your business if you provide a service and a mistake causes financial loss for someone else? This is where a product called Errors and Omissions coverage fills the protection gap....

Continue Reading

Thursday, September 6, 2012

SINKHOLE INSURANCE!!! GET YOUR SINKHOLE INSURANCE HERE!


The recent sinkhole on the 174 east, close to Orleans, has generated some interest about insurance…… yes, you read that right - INTEREST ABOUT INSURANCE!.  Various comments appeared on twitter and facebook like a few samples below:


Sooooo…. Let’s see if we can shed some light on the situation.  Remember that every situation is unique, you should talk to your insurance broker, and we only know the details about this specific case, that we can read in the newspaper.

Although the ultimate decision about claims rests with the particular insurance company, in this type of situation, we would expect the claim would handled under the loss or damage section of the policy as a collision.

If the person in question did not have collision insurance at the time of the accident, they would be financially responsible for the loss of the vehicle. They would also have to pay for their own rental vehicle (if required) and have to purchase a replacement vehicle at their own expense. They would also be responsible for the costs involved in recouping the lost funds from the province, if that was an option they wished to pursue. This would take time and money.

If the person in question had the full, appropriate physical damage coverage on the policy at the time of the accident, the insurance company would cover the loss of the vehicle, according to the terms of the insurance policy. They would also pay for a rental vehicle (assuming that coverage had been purchased), giving the client sufficient time to find a replacement vehicle. The claim would be subject to the policy deductible.

Since the collision was a single car accident, it is technically considered to be an at fault claim. However, in situations such as these, the outcome of the claim would be handled on a case by case basis. A thorough investigation would take place in order to properly negotiate the settlement with the claims adjuster.

If the insured sustained injuries (which fortunately in this case, I understand that they were only very minor) from the accident he/she would be entitled to compensation under the accident benefits portion of the policy up to a certain limit. The option to increase accident benefits on an automobile policy is available for all licensed drivers in Ontario. Increasing this coverage comes with a minimal cost but could help protect you and your loved-ones in the event of a catastrophic accident.

Wednesday, September 5, 2012

Sinkhole, in Ottawa?

If you ever needed a reminder that insurance claims can happen in an instant and can come out of nowhere, this very unusual local story proves it.

Yesterday afternoon, a man was driving home eastbound on Highway 174. He took his usual route home, and was proceeding to take the Jeanne D’Arc exit.  However, on this rainy Tuesday, there seemed to be something blocking the exit ramp. At first glace, the man thought there may be a tarp spread out on the road. As he approached the unidentified object, he quickly discovered it was a large hole!


With no room to stop without causing a major accident, his car fell into the large sinkhole.  His options were bleak, the likelihood of another vehicle falling into the hole and crushing him were high. Although the odds were stacked against him, he still managed to get his car door open and crawled out. Alive and safe with only minor injuries reported!

We never know when Mother Nature will strike. Flowing water can have many dangerous consequences. Luckily, the man escaped with only a couple bruises and scrapes. However, the situation could have been far more disastrous. Although we have no way of predicting the probability of a loss, it’s important to have proper coverage on your policy to help protect you and your loved-ones.

Please see our follow-up blog to learn how Insurance would handle an accident like this.

This article was written by Geneviève St-Denis from Rhodes & Williams Insurance Brokers.